

Netspend

- 22.16K Reviews
- 4.6
- Downloads
- 10,000,000+
Our take on Netspend from Appgk
I found Netspend most useful when I stopped thinking of it as a complete replacement for every banking tool and started treating it as a practical way to manage a separate spending account. In a household, that distinction matters. A shared tablet, a partner’s phone, or a family member who needs access to a particular pool of money can make financial apps awkward, especially when everyone’s accounts and responsibilities are mixed together. Netspend gives that arrangement a clearer boundary, provided each person understands exactly whose account it is and what the app is being used for.
This is a free finance app from Netspend Corporation, and its simple purpose is reflected in the short store description: “Netspend.” The broader promise, “Your Money, Your Way,” sounds flexible, but in practice I think the value comes from making everyday money management more deliberate. It is aimed at people using Netspend services rather than anyone looking for a general-purpose budgeting app, investing platform, or full household finance dashboard.
It has been available since May 23, 2011, and its current version is 7.0.15. The app is rated for Everyone and requires iOS 9 or later, which makes it approachable from an age-rating perspective and compatible with older Apple devices. Its popularity is also substantial: it has more than 10 million installs, around 175 thousand ratings, and roughly 22 thousand written reviews, with an average rating of 4.6. Those figures suggest that many people find the service useful, although popularity alone does not remove the need to check whether its account model fits your situation.
How Netspend Works in a Shared Household
My most realistic household scenario is a couple managing regular spending without wanting to hand over access to every financial detail. One person might use Netspend for groceries, transport, or a recurring personal allowance, while the other keeps separate responsibility for rent, savings, and bills. The app can then serve as the place to check the balance and review activity for that specific spending purpose, rather than becoming a window into the entire household’s finances.
Best Parts of Netspend
Things to Keep in Mind About Netspend
That separation is the first important advantage. A shared device does not automatically mean a shared account should be used by everyone. If Netspend is installed on a family tablet, I would be careful about leaving the account open between uses. A person checking a balance may be comfortable doing so in front of a partner, but that does not mean the same device should remain available to children, visitors, or anyone else who can pick it up. The household arrangement works best when the app is treated as personal financial access, even if the hardware is communal.
I also like the idea of using a dedicated spending balance for a defined purpose. For example, a household could decide that one Netspend account is used for weekly food shopping while another account handles personal purchases. That is not the same as a built-in family budgeting system, and I would not present it as one. The benefit comes from the human agreement around the account: everyone knows what the money is for, and the app provides a place to check activity instead of relying on memory or scattered messages.
News and Features Related to Netspend

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The trade-off is that coordination still depends on communication. Netspend does not magically decide whether a purchase belongs to the household or to one person. If two people use the same account without agreeing on limits, the balance can become confusing quickly. I would write down the purpose of the account, who is allowed to use it, and what happens when a purchase is made for someone else. That small step prevents the app from becoming another source of arguments.
Setting boundaries before anyone shares access
Before installing Netspend on a shared device, I would decide whether the account is genuinely shared or merely being viewed by another trusted adult. Those are different arrangements. A person who only needs to see available money should not necessarily be given the same practical access as the account holder. I would also avoid assuming that a household can create child-friendly access simply because the content rating is Everyone. The age label describes the app’s general suitability, not a complete system for teaching children to manage money.
Don't want to read the full review?
The safest setup is one where the account owner remains clear. If a partner helps with household spending, both people should know whether they are checking the same account, using separate accounts, or simply discussing transactions outside the app. I would not put multiple people’s credentials into a notes app or leave them beside a shared device. Netspend can be useful in a household, but the account boundary has to come from the people using it.
Another practical boundary is purpose. I would not use one balance for groceries, school expenses, entertainment, and emergency spending unless everyone is comfortable sorting those uses afterward. A separate spending purpose makes the balance easier to interpret. When the money is low, you can ask a straightforward question: was it used for the agreed category, or did the account quietly become a general wallet?
Screenshots
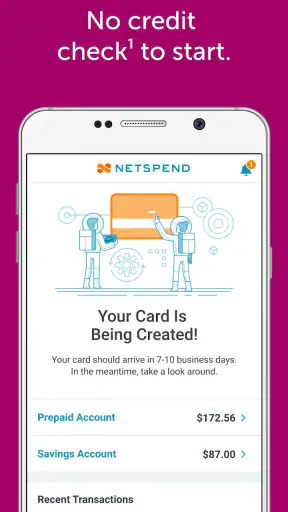
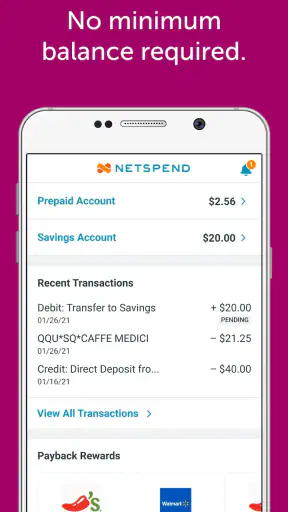
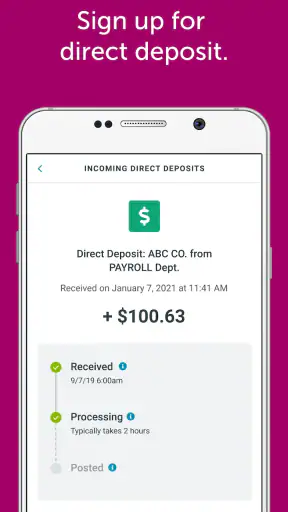
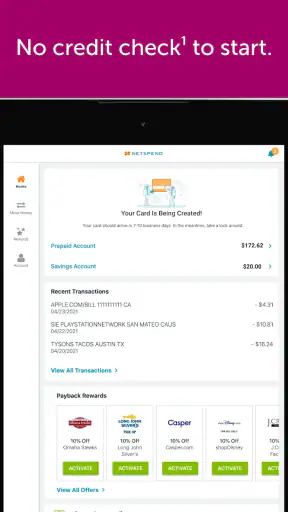
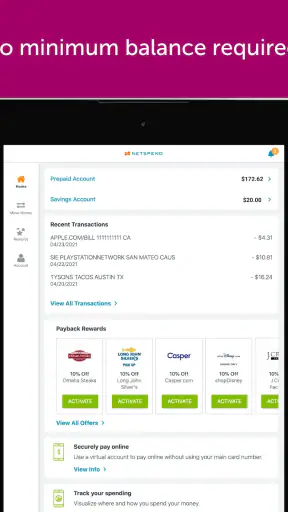
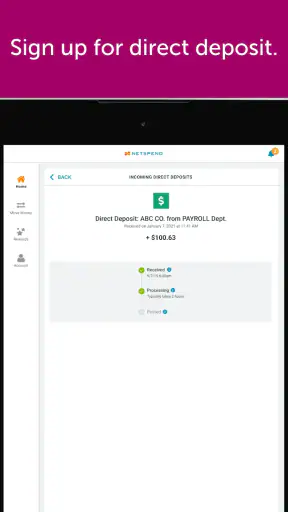
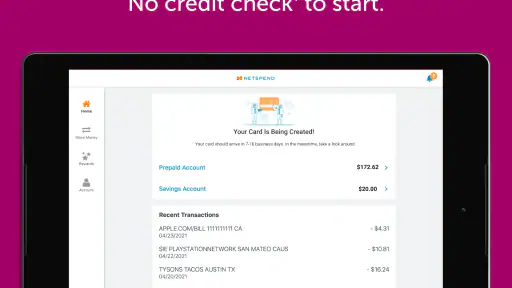
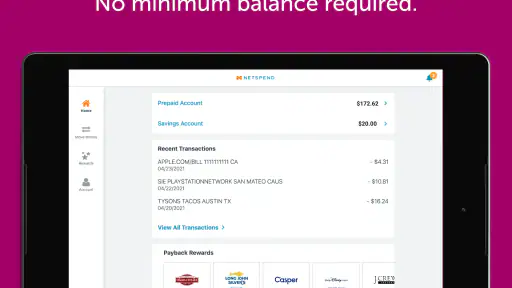
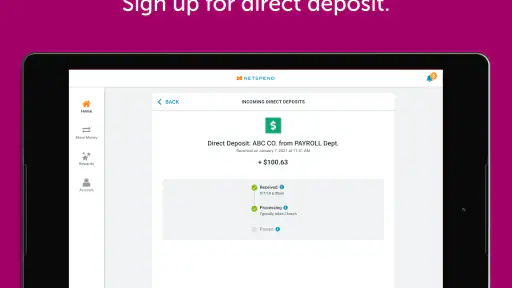
This approach also helps when one person is less confident with financial apps. Instead of trying to explain every part of a family’s finances, you can show that person how to open Netspend, check the relevant balance, and review recent activity. That narrower lesson is easier to understand than a broad tour of multiple bank accounts, credit cards, and budgeting tools.
Using the app to coordinate everyday spending
In daily use, I would make checking the balance part of the shopping routine rather than waiting until checkout. If one household member is heading to the supermarket, they can review the account first and tell the other person whether the planned purchase fits the available money. This is a small workflow, but it is more reliable than assuming someone else has already checked.
For shared errands, I would agree on how to describe purchases. “Groceries” may be enough for a normal shop, but a larger transaction could include household supplies, a personal item, and a gift. When reviewing activity later, a short message between household members can provide context that the transaction list alone may not. The app helps with visibility; it does not replace the household’s own record-keeping.
One less obvious strength is that a focused account can reduce the temptation to make decisions from a total household balance. Seeing a dedicated spending amount encourages more realistic choices. If the account is meant for food, the question becomes whether the food budget can cover the trip, not whether money exists somewhere else. That psychological separation is useful for people who find a single combined balance too vague.
There is also a useful exception. If your household needs detailed category reports, long-term savings targets, investment tracking, or a combined view of several institutions, Netspend is unlikely to be enough on its own. A traditional bank app or a dedicated budgeting service may be better for that broader picture. I would use Netspend for the account it represents and pair it with another method only when the household genuinely needs a wider overview.
Coordination becomes harder when people use the app at different times and do not discuss pending plans. One person may assume money is available because a purchase has not appeared yet, while another has already committed to an expense. I would leave a small buffer rather than treating every visible dollar as immediately spendable. That is a household habit, not a special feature, but it makes shared use less fragile.
Age, trust, and the difference between visibility and control
The Everyone rating makes Netspend appear approachable for a broad audience, but I would separate age suitability from financial readiness. A teenager might understand how to open an app and read a balance without being ready to make independent spending decisions. An older relative may be comfortable with the concept of a prepaid-style spending account but still need help recognizing when they are viewing or using the wrong account.
For that reason, I would introduce Netspend to a younger household member through a narrow, supervised task: checking the available amount before a planned purchase or confirming that a transaction belongs to the agreed spending category. I would not treat the app as a substitute for parental guidance, and I would not assume that the age rating provides family controls, allowance tools, or automatic restrictions. Those expectations should be settled before the account is shared.
Trust is equally important between adults. If a partner is allowed to use the account, both people should agree whether that permission includes purchases, balance checks, or only occasional help. A shared device can blur those lines. The cleanest arrangement is to discuss access openly and avoid presenting a personal account as a communal one when it is not.
I also think Netspend is more suitable for a defined relationship than for a large informal group. It may work for two trusted adults coordinating a particular household expense, but I would avoid using one account among roommates who have different ideas about reimbursement. In that case, a shared expense tracker or a bank arrangement designed for joint ownership may provide clearer responsibility. Netspend can show activity, but it cannot settle disagreements about who owes what.
Older devices are another practical consideration. The minimum operating system is iOS 9 or later, so the app may be accessible on hardware that is not recent. That can help a household reuse an older iPhone or iPad, but I would still keep the software and device protected as far as possible. A compatible device is not automatically a secure shared device, especially if it is left unlocked in a common room.
Where it fits beside ordinary banking alternatives
Compared with a conventional bank app, Netspend feels more focused on the particular Netspend account rather than on presenting a complete relationship with a bank. That can be an advantage for someone who wants a straightforward spending boundary. A full bank app is usually the better choice when you need mortgages, multiple account types, detailed transfers, or a broad view of household finances in one place.
Compared with a budgeting app, Netspend is closer to the money itself than to a planning worksheet. A budgeting tool may let you organize accounts, set categories, and compare spending over time, while Netspend is more useful for checking the account connected to its service and understanding what is happening there. I would not choose it solely because I want sophisticated financial planning.
Compared with a shared spreadsheet, Netspend reduces the need to manually enter every account event, but it also gives the household less freedom to design its own categories and rules. A spreadsheet can explain why a purchase was made and how a reimbursement should be divided. Netspend is better when the main question is the account’s current activity, not when the household wants to build a custom accounting system.
The most sensible combination depends on the household. Someone may use Netspend for controlled everyday spending and a separate budgeting method for rent, savings, and annual expenses. That is not redundant if each tool has a clear job. Problems arise when people expect the app to provide the planning depth of a finance organizer or the shared ownership structure of a joint bank account.
Small habits that make the experience clearer
I would begin by naming the purpose of the account in plain language outside the app: “weekly groceries,” “personal spending,” or “travel money.” Then I would check activity at a consistent time, such as after shopping or before planning the next purchase. This creates a simple rhythm and makes unusual activity easier to notice.
For a shared device, I would avoid leaving the app open after checking the balance. I would also keep the device in a place where private financial information is not casually visible. These steps may sound obvious, but they matter more than adding another app to a crowded household routine.
A second useful habit is to separate planned spending from available spending. If a household member has promised to buy something later, that amount should be mentally reserved even if the balance still shows it. Netspend can help you see what has happened, but the household still needs to account for what is about to happen.
Finally, I would review whether the account arrangement still makes sense after a few weeks. If everyone keeps asking who used the money, the boundary is too vague. If one person needs broader access, a different account structure may be more appropriate. The app should simplify coordination, not force the household to maintain a complicated set of explanations.
My household verdict
After using Netspend as a focused finance app, I see its strongest role in controlled, everyday spending where the account’s purpose is easy to explain. It can be a sensible choice for a person who wants a separate balance, a couple coordinating one category of household expenses, or a family member who needs a simple way to check activity without navigating a full banking ecosystem.
I would skip it as the main household solution if your priority is joint ownership, advanced budgeting, investment management, or a single dashboard covering every financial obligation. I would also avoid treating the Everyone rating as proof that children can use it independently. The account holder, access rules, and spending expectations still need to be handled by real people.
My final view is positive but deliberately practical: Netspend works best when its boundaries are clearer than the household’s overall finances. Use it for a defined spending job, keep shared-device access thoughtful, and pair it with another tool when you need detailed planning. For that focused role, I can recommend Netspend to a friend; I just would not describe it as a complete answer to every family money problem.
Netspend FAQ
What is Netspend, and what can I use it for?
Netspend is a prepaid financial service that can help you manage spending without opening a traditional bank account. Depending on the card and services available in your area, you may use it for purchases, direct deposit, bill payments, money transfers, and ATM withdrawals. The Netspend app provides access to balances, transaction history, alerts, and card-management tools, although available features can vary by account type and location.
Is the Netspend app free to download and use?
The Netspend app is generally free to download, but downloading the application does not mean that every service is free. Fees may apply for monthly plans, ATM withdrawals, cash reloads, expedited transfers, or certain card transactions. Before using the account, review the current fee schedule shown by Netspend, because charges can differ depending on your card program, plan, retailer, and transaction method.
How do I add money to a Netspend account?
There are several ways to fund a Netspend account, including direct deposit, bank transfers, mobile check options where available, and cash reloads at participating locations. Each method may have different processing times, limits, and fees. Direct deposit can be convenient for recurring income, while cash reloads may be useful for people who prefer handling money in person. Always confirm availability in the app.
Is Netspend safe for everyday purchases and managing money?
Netspend includes security tools such as account login protection, transaction monitoring, card controls, and alerts that can help you notice activity quickly. However, a prepaid account should still be used carefully. Protect your password and card details, avoid sharing verification codes, and contact Netspend promptly if you notice an unfamiliar transaction. Security features and protections may depend on the specific card and situation.
Can I use Netspend internationally or withdraw cash from any ATM?
Netspend cards may be usable at participating merchants and ATMs, but international acceptance, currency conversion, and withdrawal availability depend on the card network and account terms. ATM operators and Netspend may charge separate fees, and some locations may not accept the card. Before traveling, check the app or official fee disclosures for supported countries, international charges, withdrawal limits, and card restrictions.











